Who Controls Food Waste Metrics in 2027 Independent Restaurant Profitability
Amsterdam bistro groups cutting food costs 6-9% reveal a structural shift: waste metrics now belong to finance, not the kitchen. This piece maps who owns the numbers in 2027 and why it decides profitability.
Who Controls Food Waste Metrics in 2027 Independent Restaurant Profitability
A six-location bistro group operating across Amsterdam's Jordaan, De Pijp and Oud-West neighborhoods cut its food cost percentage from 32 percent to 24 percent in fourteen months. The lever was not a new menu, a renegotiated supplier contract, or a staffing cut. It was a decision to move waste tracking out of the kitchen and into the finance function, pairing automated inventory-to-plate sensors with weekly profitability reviews led by a controller rather than a chef. Net margins across the group rose from 4.1 percent to 9.6 percent in the same window, according to internal reporting shared with regional operators' associations.
That single operational change illustrates the thesis driving restaurant economics through 2026 and 2027: operators who treat food waste as a primary financial KPI, owned and reported the way labor cost or rent is owned and reported, consistently outperform operators who leave it as a kitchen-level operational afterthought.
The Hidden Cost of Waste in Modern F&B
Industry waste in independent restaurants typically runs between 4 and 10 percent of total food purchases, but the financial exposure is larger than the raw percentage suggests. At current ingredient inflation rates across Western Europe and North America, a restaurant purchasing 40,000 euros of food monthly and wasting 8 percent is losing roughly 3,200 euros every month, or nearly 38,400 euros annually, before any analysis of why the waste occurred.
The Amsterdam group's data showed something operators rarely quantify: nearly 60 percent of plate and prep waste was traceable not to kitchen error but to purchasing decisions made three to five days earlier, when ingredient prices or delivery volumes shifted without anyone adjusting production forecasts. That gap between purchasing and plating is where financial accountability now lives.
Why Traditional Waste Reporting Fails P&L Statements
Most independent restaurants still log waste on paper sheets or spreadsheets maintained by sous chefs at the end of a shift. This model fails the P&L in three specific ways.
First, timing. Waste logged at shift end is reconciled days or weeks later, long after the ingredient pricing window that caused the loss has closed. Second, ownership. Kitchen staff logging their own waste have limited incentive to flag it accurately, since it reflects on their station performance. Third, format. Waste logs rarely map to a chart of accounts, so a general manager or owner sees a waste percentage but cannot connect it to gross margin, contribution margin, or cash flow forecasts.
The result is a reporting structure that satisfies kitchen operations but tells an owner almost nothing about where money is actually leaking. A controller reviewing a monthly P&L sees food cost variance but no causal link to specific ingredients, shifts, or suppliers.
Transitioning From Operational Oversight to Financial Accountability
The structural fix emerging across Dutch, American and Malaysian independent groups in 2026 is a reporting realignment. Waste data no longer terminates with the Executive Chef. It routes to a Financial Controller or F&B Cost Analyst who reports directly to ownership or a General Manager with P&L responsibility.
| Role | Reports To | Primary KPI Owned | Decision Authority |
|---|---|---|---|
| Line Cook / Prep Cook | Sous Chef | Portion accuracy, prep yield | None, execution only |
| Sous Chef | Executive Chef | Station waste logs, labor efficiency | Station-level adjustments |
| Executive Chef | General Manager | Menu cost, recipe standardization | Menu design, supplier selection input |
| F&B Cost Controller / Financial Analyst | General Manager or Owner | Waste-to-revenue ratio, ingredient price variance | Purchasing approval thresholds |
| General Manager | Owner / Managing Partner | Net margin, labor-to-food cost blend | Budget reallocation |
| Owner / Managing Partner | Board or self | Overall profitability, expansion decisions | Capital allocation |
This is not a demotion of the kitchen. Executive Chefs retain full authority over menu creativity, recipe standardization and supplier relationships. What changes is who owns the financial interpretation of waste data and who has authority to act on pricing volatility before it reaches the plate.
Hiring patterns confirm the shift. Independent groups with four or more locations are increasingly creating a standalone F&B Cost Controller role, distinct from bookkeeping, with salary bands in the Netherlands ranging from 45,000 to 65,000 euros annually, and US equivalents between 55,000 and 80,000 dollars depending on market and group size. This role typically sits between the General Manager and Executive Chef in reporting structure, with dotted-line access to ownership for monthly variance reviews.
Integrating Automated Tracking With Real-Time Ingredient Pricing
The Amsterdam case worked because waste tracking was not treated as a standalone sensor project. It was integrated with real-time ingredient pricing feeds from the group's three primary distributors. When cauliflower prices spiked 22 percent over ten days due to a regional supply disruption, the system flagged the variance and automatically adjusted portion-cost projections before the next prep shift, rather than after a month-end report revealed the margin hit.
This integration requires three components working together rather than in isolation.
- Weight-based or camera-based waste capture at prep and plate return stations
- A pricing feed from suppliers updated daily or in near real time
- A dashboard accessible to both the Cost Controller and General Manager, not siloed in a kitchen-only system
Groups that implemented only the sensor component without the pricing integration saw waste percentage improvements of 2 to 3 points. Groups that integrated both saw improvements of 6 to 9 points, because staff and management could see the financial consequence of a waste event within hours rather than weeks.
Building a Culture of Profitability Across the Culinary Team
Financial accountability for waste only works if culinary teams understand the connection between their actions and the numbers a controller reviews. Groups seeing sustained improvement built this understanding through structured, recurring communication rather than one-time training.
A practical checklist operators are using heading into 2027:
- Weekly fifteen-minute huddles pairing the Sous Chef and Cost Controller to review the prior week's top three waste variances
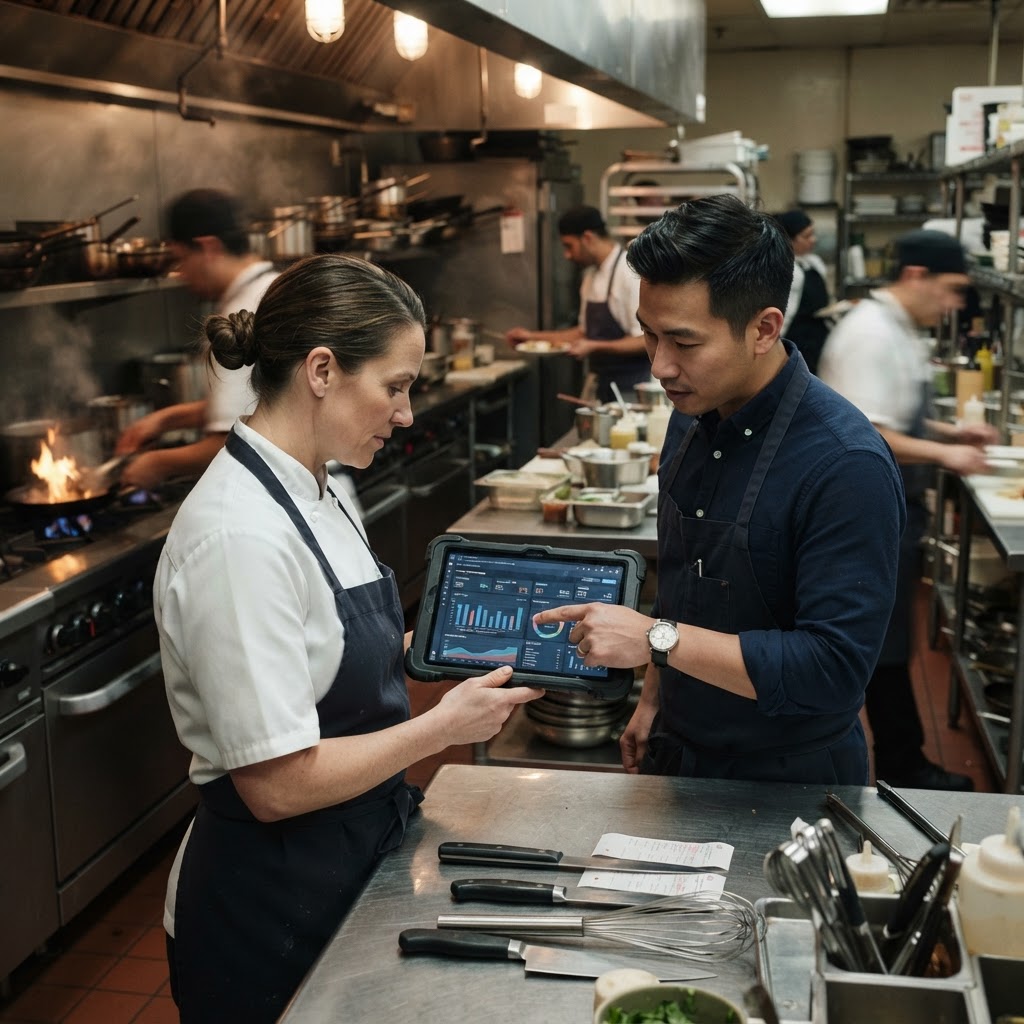
- Shared dashboards visible on kitchen tablets showing real-time waste cost in currency, not just percentage
- Incentive structures tying a portion of kitchen team bonuses to waste-to-revenue ratio improvements, not just food cost percentage
- Clear escalation paths so a Sous Chef flagging a pricing anomaly reaches the Cost Controller within the same shift, not the next reporting cycle
- Quarterly cross-training sessions where Executive Chefs walk Cost Controllers through recipe changes, and Cost Controllers walk chefs through margin impact
The groups that struggled with adoption treated this as a compliance exercise imposed on the kitchen. The groups that succeeded treated it as a shared financial language, with the Executive Chef functioning as a translator between creative execution and the controller's numbers.
Benchmarking 2027 Waste Metrics for Scalable Growth
As independent groups scale past three or four locations, waste benchmarking becomes a prerequisite for raising capital or securing favorable lease terms, since investors and landlords increasingly request waste-to-revenue data alongside standard financial statements.
Operators preparing for 2027 growth are benchmarking against three tiers:
- Waste percentage under 5 percent of total food purchases, considered scalable and investor-ready
- Waste percentage between 5 and 8 percent, considered functional but requiring active management before expansion
- Waste percentage above 8 percent, considered a structural risk that will compress margins further as ingredient inflation continues through 2027
Groups scaling successfully are also separating waste metrics by category, kitchen prep waste, plate return waste, and spoilage waste, since each has a different owner and a different corrective action. A controller who can isolate spoilage waste as a purchasing and storage issue, distinct from plate return waste as a menu or portion issue, gives ownership far more actionable data than a single blended percentage.
Conclusion
The restaurants outperforming their peers through 2026 and 2027 are not necessarily the ones with the most talented kitchens. They are the ones that rebuilt their reporting structure so waste data flows to the people with financial authority to act on it, in near real time, integrated with live ingredient pricing. The thesis holds across markets: when waste becomes a financial KPI owned by a controller and reviewed weekly with ownership, net margins improve in ways that waste logs alone never produced.
Operators and F&B managers evaluating their own structure should ask a direct question: who in your organization currently has both the data and the authority to act on a waste variance within the same week it occurs. If the honest answer is nobody, that gap is costing more than most owners realize.
USHMU's Advanced F&B Cost Control and Financial Management certificate program was built for exactly this transition, equipping operators and rising managers with the financial frameworks to own waste metrics as a core profitability lever rather than a kitchen afterthought.
FAQ
Who should own food waste metrics in an independent restaurant, the chef or a financial role? Waste data collection remains a kitchen responsibility, but financial interpretation and corrective authority should sit with a Cost Controller, General Manager, or Financial Analyst who reports directly to ownership and can connect waste variance to margin in real time.
What waste percentage should a restaurant target in 2027? Most benchmarking frameworks consider under 5 percent of total food purchases scalable and investor-ready, 5 to 8 percent functional but requiring active management, and above 8 percent a structural risk given continued ingredient inflation.
How does automated waste tracking actually improve net margin? It shortens the gap between a waste event and a financial response. Groups integrating automated tracking with real-time ingredient pricing saw margin improvements of 6 to 9 percentage points, compared to 2 to 3 points for sensor-only implementations without pricing integration.
Do kitchen staff need financial training to support this model? Not formal financial training, but they need regular, structured exposure to the financial consequence of waste, typically through shared dashboards and weekly huddles with a Cost Controller, so waste reduction becomes a shared incentive rather than an imposed audit.
Is this shift relevant to single-location independent restaurants, or only multi-unit groups? Single-location operators benefit as well, though the dedicated Cost Controller role often becomes a part-time or fractional function until the business scales to a size that justifies a full-time hire, typically around three to four locations or equivalent revenue volume.
Explore USHMU Programs
Discover degrees and certifications across hospitality, business, and applied AI.
Browse Academic Catalog